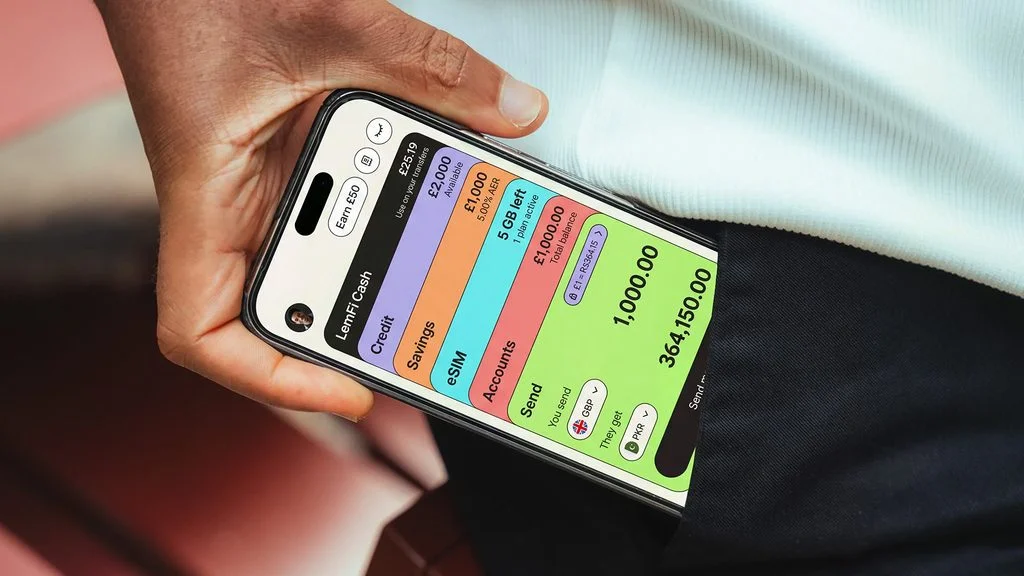
LemFi’s redesigned app brings transfers, UK savings and credit, and eSIM data into one account, as the company broadens its services for people living across borders.

LemFi’s latest expansion pushes the company beyond international transfers toward a single account for customers whose financial lives span countries. The rebuilt app brings together payments, UK savings and credit, and eSIM data. The company frames the shift with a new brand platform, “Ambition has no passport,” and a broader claim: that customers shouldn’t have to split their financial lives across separate services simply because they cross borders.
More than two million customers use LemFi to send money to over 30 countries. The company reports monthly transaction volume above $2 billion and plans to add more destination countries next year. Those figures give the expansion an existing payments base to build on, though transaction volume alone doesn’t show how many customers will adopt the new products. Savings and credit are available in the UK, while mobile data access covers more than 100 destinations.
Building around customers who cross borders
The product strategy responds to a familiar friction for people who move countries: their qualifications, savings and financial records may not carry the same weight in a new home. An estimated 304 million people live outside the country where they were born, sending about $905 billion home each year. Those figures point to a large group with financial ties in more than one place, but remittances are only one part of that activity.
Many financial products still assume that customers earn, spend and build credit in one country. That assumption can leave people managing separate accounts, payment methods and records as they settle somewhere new while continuing to support family or business ties elsewhere. A single app could reduce some of that friction, provided the services fit the customer’s needs and work reliably across different markets.
LemFi was founded on international transfers. CEO and co-founder Ridwan Olalere said the company came to see the transfer itself as only the beginning of customers’ financial needs. “Our customers are building careers and businesses in one country while supporting people in another, and the financial system treats them as if they can only exist in one place at a time,” he said. The redesigned platform is meant to serve more of that activity through one account. That’s a meaningful change in ambition, though its value will depend on whether customers use the additional services, not just the transfer feature that brought them to LemFi.
What the expanded account includes
International transfers remain at the center of LemFi’s offering, covering more than 30 countries across Africa, Asia, Europe and other regions. Customers can now access the new services alongside those transfers, giving the app a wider role in everyday financial tasks. The mix is notable: savings and credit address longer-term financial needs, while eSIM data is a practical travel service with a different use pattern.
In the UK, LemFi’s Instant Access Savings Account pays a promotional 5% AER for the first six months after opening, then changes to a variable tracker rate currently at 3.04% AER. Customers can open an account with £1 and withdraw without a penalty. ClearBank holds deposits, which are protected by the Financial Services Compensation Scheme up to £120,000 per eligible depositor. The promotional rate gives customers a clear reason to compare the account, but they’ll need to pay attention to the rate that applies after the first six months.
The UK credit offering is a revolving line issued by Lemfi Credit through Pillar, a credit provider LemFi acquired in 2025. Availability is subject to eligibility, so access won’t be the same for every customer. Customers can use the virtual card with Apple Pay and Google Pay for purchases and transfers, while eligible users can check their Equifax credit score in the app at no cost. Putting credit access and a score check in one place may help customers track parts of their financial profile, though the product details provided here don’t explain how the credit line is priced or assessed.
For travel, the app also offers eSIM data in more than 100 destinations. Customers can buy data before arrival without changing SIM cards or incurring roaming charges. That’s a simpler proposition than the savings and credit products: it solves a specific travel inconvenience, while the financial services ask customers to make a longer commitment to the app.
A rebuilt app and a new brand
LemFi says it re-architected the app to support multiple products across multiple countries within one account. The redesign puts those services more prominently in the interface and gives the company room to add products as it enters new markets. The software work matters because adding services can make an app harder to navigate; a unified account only helps if customers can understand which product they’re using and what its terms are.
The “Ambition has no passport” platform will appear across the app, website, marketing and social channels as it rolls out globally. Isabel Ron-Pedrique, LemFi’s vice president of design and brand, said the identity reflects customers’ goals and the lives they’re building, rather than the countries they’ve left. The message gives the product expansion a coherent story, but brand language can’t resolve the underlying differences between financial systems in each market.
What the expansion needs to prove
Savings and credit are launching in the UK, with LemFi saying other markets will follow. That makes the UK the first test of whether the company can extend a cross-border payments relationship into products customers use for saving or borrowing. The categories come with different expectations: customers may judge a transfer service by speed and cost, while savings and credit also demand clear terms, eligibility and ongoing account support.
If you’re working in this space, the strategic question is whether a shared app can make multiple services feel connected without obscuring their differences. LemFi already has a payments network and a large customer base, which gives it a route to introduce new products. And yet. Distribution is only a starting point; customers still need a reason to keep each service in the account.
This is more significant than it looks if LemFi can make the account useful across the practical stages of living between countries: sending money, setting aside savings, accessing credit and staying connected while travelling. The numbers here are underwhelming as evidence of adoption, because the company hasn’t provided usage figures for the new services. The next test is whether the wider platform earns a regular place in customers’ financial lives. The pitch is clear. The proof will come from use.
Discussion
Sign in to join the discussion.